




Peak hurricane season brings deductible confusion for Baton Rouge families. Many homeowners are surprised to learn that their standard insurance deductible doesn’t always apply during hurricanes. Instead, policies often carry a separate hurricane roof damage deductible, which can affect how much you pay out of pocket after a storm.
In this educational guide, you’ll learn what a hurricane roof damage deductible is, how it’s calculated, and why it matters for Louisiana homeowners. We’ll also share local insights, customer stories, and roofer perspectives to help you prepare for hurricane season with clarity and confidence.
What Is a Hurricane Roof Damage Deductible?
In simple terms, a hurricane roof damage deductible is the amount you’re responsible for paying before your insurance coverage applies to storm-related roof repairs. Unlike flat deductibles for other claims, hurricane deductibles are usually calculated as a percentage of your home’s insured value.
For example:
- Home insured for $250,000
- Deductible set at 2%
- You would pay $5,000 before coverage begins
This percentage-based system is designed to spread risk in hurricane-prone areas like Baton Rouge, but it often catches homeowners off guard.
Why Louisiana Policies Include a Hurricane Roof Damage Deductible
Insurance companies apply these deductibles because Louisiana is at high risk for tropical storms. NOAA reports that the Gulf Coast sees multiple named storms each year, with Baton Rouge often experiencing heavy winds and rain even when hurricanes don’t make direct landfall.
For insurers, this risk is too great to cover with flat deductibles alone. That’s why many Louisiana homeowners face a hurricane roof damage deductible that is higher than their regular deductible for non-storm claims.
How to Know If Your Policy Has a Hurricane Roof Damage Deductible
Homeowners should:
- Review their insurance policy declarations page.
- Look for terms like “windstorm deductible,” “named storm deductible,” or “hurricane deductible.”
- Ask their insurance agent directly about coverage limits.
Licensed roofers like Better Built Contractors can’t interpret or negotiate insurance terms, but we can encourage you to review your documents carefully and schedule Insurance Claims documentation support when damage occurs. Contractors don’t negotiate claims, only document & repair.
A Baton Rouge Customer Scenario
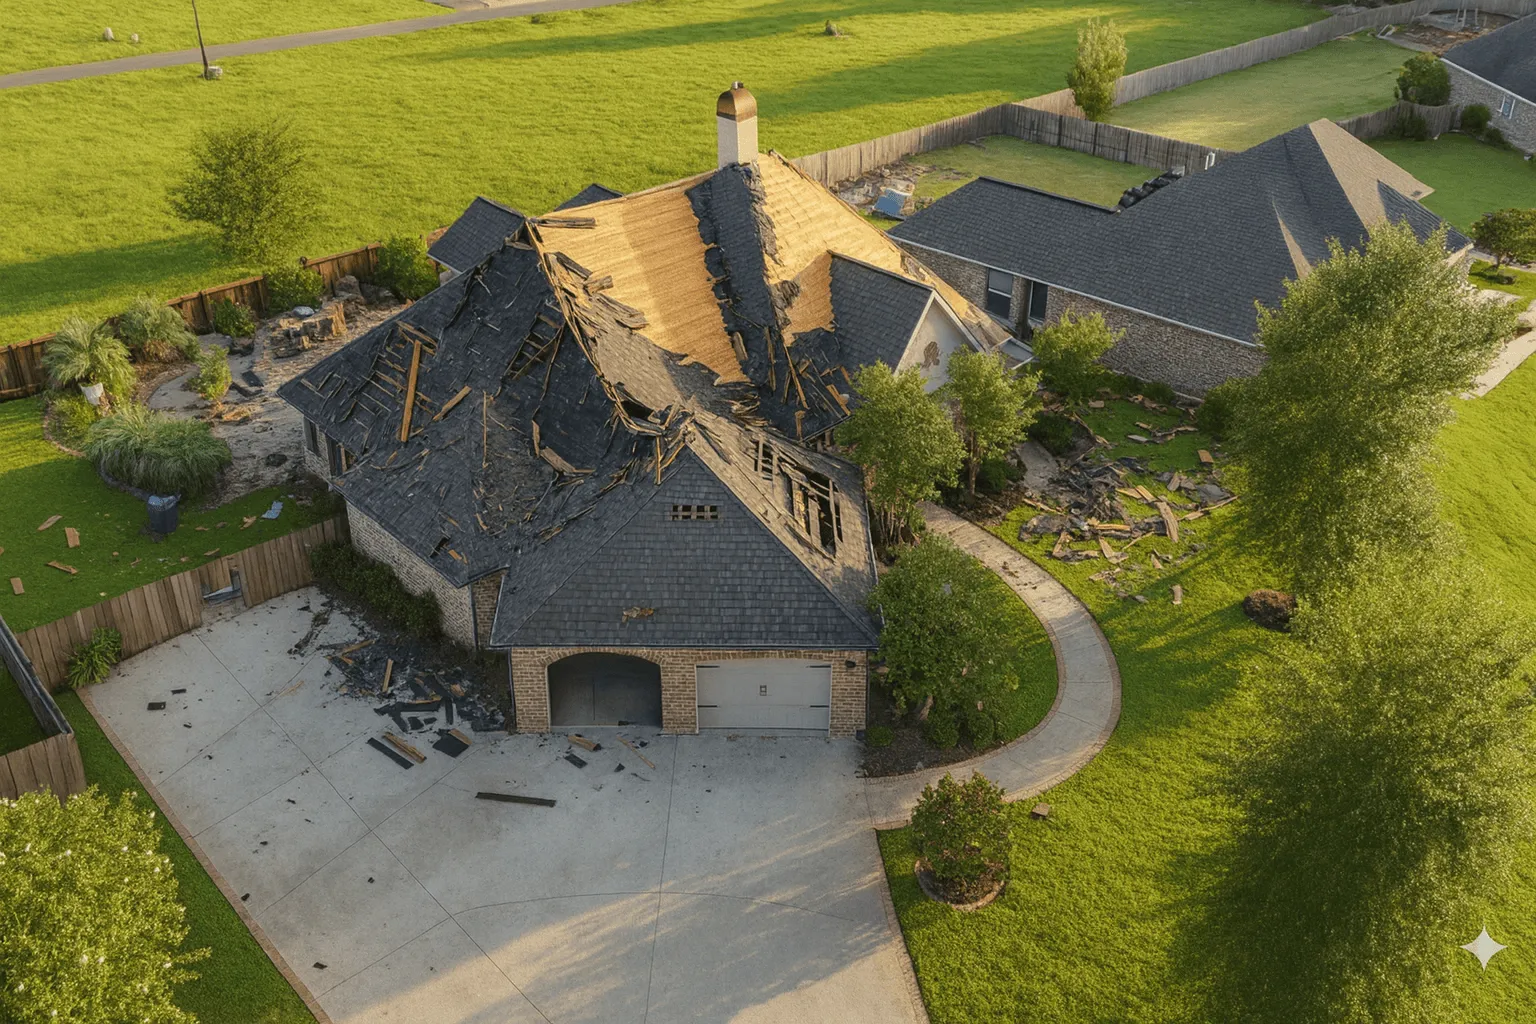
After Hurricane Ida, the Johnson family in Baton Rouge noticed shingles scattered across their yard. Their insurer confirmed coverage, but their hurricane roof damage deductible was 5% of their insured value. With a $300,000 policy, that meant they paid $15,000 out of pocket before insurance covered the rest.
This was a shock, but with proper documentation from a trusted roofing company like Better Built Contractors, they had a clear inspection report to present, which sped up the repair timeline. Their experience highlights why understanding your deductible matters as much as repairing your roof.
How Deductibles Impact Roof Repairs
When a hurricane roof damage deductible applies, it influences:
- Timing of Repairs: Homeowners may delay work until they understand costs.
- Scope of Repairs: Some choose to cover only immediate issues, leaving other vulnerabilities.
- Out-of-Pocket Costs: Larger deductibles require more upfront funds.
Local roof repair contractors Baton Rouge often advise documenting all visible damage immediately after storms to ensure nothing is overlooked when planning repairs.
Insights From Licensed Roofers
At Better Built Contractors, our roofers often remind homeowners:
- “Your deductible doesn’t fix your roof, documentation and repair do.”
- “Don’t wait for water stains to spread; document damage immediately.”
- “Every storm season, we see families caught off guard by their hurricane roof damage deductible, knowledge is your best defense.”
We’ve seen Baton Rouge homes damaged by both Category 1 hurricanes and weaker storms that still carried high winds. Every roof reacts differently depending on its age, materials, and prior maintenance.
How to Prepare Before Storm Season
Here are steps to reduce stress:
- Schedule a pre-season inspection to document your roof’s condition.
- Clear gutters and trim trees to reduce impact risk.
- Ask your agent about your exact hurricane roof damage deductible.
- Keep digital and printed copies of your insurance documents.
By combining preventative care with documentation, you protect yourself financially and physically.
Deductible Percentages Explained
Most Louisiana policies set hurricane roof damage deductibles between 2% and 5%. That may sound small, but the math adds up quickly.
- $200,000 insured value with 2% deductible = $4,000 out of pocket
- $350,000 insured value with 5% deductible = $17,500 out of pocket
That’s why local homeowners are encouraged to plan ahead.
Local Weather Challenges in Baton Rouge
Hurricane season isn’t the only threat:
- Summer hailstorms dent shingles and flashing.
- Sudden monsoons overwhelm valleys and gutters.
- High humidity keeps roofs damp, weakening wood.
Better Built Contractors combines local weather knowledge with professional roofing experience, making us a trusted partner for Baton Rouge homeowners navigating the challenges of a hurricane roof damage deductible.
The Role of Documentation
The key isn’t just knowing your deductible, it’s having accurate documentation when storms hit. Our inspection process includes:
- Photos of all roof surfaces.
- Notes on flashing, valleys, and ventilation.
- Reports suitable for homeowner records.
We provide the facts, so you’re prepared when discussing coverage. Remember: our role is to document and repair, not negotiate your policy.
Local Authority and Experience
Better Built Contractors has served Baton Rouge and surrounding communities for years. Families trust us because we combine certified roofing expertise with deep local weather knowledge. When hurricanes hit, we’re ready to document, repair, and restore homes quickly.
Visit us in Denham Springs, Louisiana to see why neighbors choose Better Built Contractors for trusted roofing solutions.
Conclusion – Take Action Before the Storms
Peak season is here, and deductible confusion doesn’t need to add stress to an already dangerous time. By understanding your hurricane roof damage deductible, preparing ahead, and working with trusted roofers, you protect your family’s home and finances.
Request a documented roof inspection for peace of mind this season.
Frequently Asked Questions
What is a hurricane roof damage deductible?
It’s the percentage of your home’s insured value you must pay before insurance covers hurricane-related roof damage.
Does every Baton Rouge homeowner have one?
Not always, but most Gulf Coast policies include them. Check your declarations page.
Can contractors negotiate my deductible?
No. Contractors only document and repair. Negotiation must be done directly with your insurer.
How high can a deductible be?
Most range from 2% to 5% of insured value, but amounts vary by policy.
What’s the best way to prepare for hurricane season?
Schedule a documented roof inspection and confirm your hurricane roof damage deductible with your insurer.